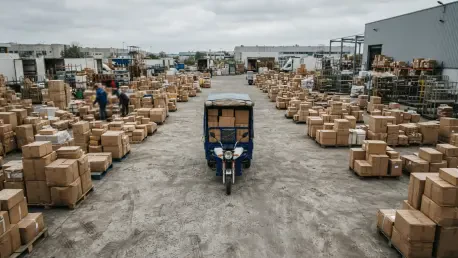
A single month of failing to meet a ninety percent service compliance rate during the Spring Festival resulted in a staggering 270,000 yuan fine for one seasoned operator. This financial blow served as the final catalyst for Wang Bing, a veteran franchise owner who represented the second generation of a family-run courier business in China. Despite the outward appearance of success, with daily parcel volumes reaching unprecedented highs, the underlying economics of the operation had become increasingly untenable. Wang Bing eventually chose to sell his delivery outlet for 4 million yuan just two months before the annual Double 11 shopping festival, typically the busiest period of the year. This voluntary exit by an experienced market participant highlights a systemic crisis within the traditional franchise-based logistics model. As the Chinese e-commerce landscape transitions into a more mature and saturated phase, old strategies of reckless expansion and volume-driven growth are failing to provide sustainable margins for the grassroots outlets that form the backbone of the national delivery network.
The Evolution: From Humble Beginnings to Scale
The historical trajectory of Wang Bing’s family business provides a clear window into the broader evolution of the Chinese courier industry over the last two decades. Established by his mother in 2005, the outlet began its journey when the digital economy was still in its infancy. With a modest initial franchise fee of only 20,000 yuan, the operation started with a single tricycle and a small team of three couriers. During these early years, the industry was characterized by low competition and high manual labor, yet the potential for growth was immense. As e-commerce platforms began to revolutionize consumer behavior across the country, the courier sector became a foundational pillar of this new economic order. The family business grew in lockstep with the market, transitioning from a localized manual operation into a sophisticated regional hub that eventually employed dozens of people and utilized advanced technological infrastructure to manage the rising tide of consumer demand.
By the time the industry reached its golden era between 2011 and 2017, the outlet was experiencing exponential growth that mirrored the broader national trend. Parcel volumes often doubled year-over-year, and annual profits for successful franchise owners frequently exceeded one million yuan. This era solidified the reputation of courier franchises as reliable wealth-building vehicles for entrepreneurial families. By 2024, the business had scaled to handle an average of 40,000 incoming and 20,000 outgoing parcels every single day, supported by a staff of 65 dedicated couriers and a significant investment in automated sorting equipment. However, this massive scale also introduced new layers of complexity and risk. The capital-intensive nature of maintaining such high throughput meant that even minor fluctuations in fee structures or labor costs could have devastating impacts on the bottom line, setting the stage for the economic erosion that ultimately led to Wang Bing’s departure from the industry he helped build.
The Financial Shift: Decoding the Volume Paradox
The core of the current crisis lies in a perplexing economic paradox where increasing parcel volumes are directly correlated with decreasing profitability for franchise operators. A pivotal moment for many grassroots outlets occurred in mid-2024 when several major courier headquarters issued notices reducing the delivery fee per parcel by a seemingly small margin of 5 cents. While such a reduction appears negligible on the surface, the mathematical reality for high-volume outlets is catastrophic. For an operation like Wang Bing’s, which processed approximately 1.2 million parcels every month, this 5-cent drop translated into an immediate annual revenue loss of 720,000 yuan. This reduction occurred without any corresponding decrease in operational costs, such as rent, fuel, or labor, effectively stripping the business of its net profit margin and forcing the owner to subsidize the delivery network’s growth out of his own capital reserves.
In addition to the erosion of per-parcel fees, a punitive fine system has emerged as a primary drain on the financial resources of franchisees. Corporate headquarters have increasingly relied on automated performance assessments to enforce strict service standards, but these systems often fail to account for regional operational realities. In early 2025, the fine of 270,000 yuan imposed on Wang Bing’s outlet for failing to meet a ninety percent compliance rate during the Spring Festival holiday illustrated the severity of this issue. These penalties can reach nearly 10,000 yuan per day, effectively wiping out any potential gains from high-volume periods. When combined with the high cost of labor compliance and the requirement for continuous technological upgrades, these fines create a situation where franchisees are essentially paying for the privilege of working harder, leading to the common industry refrain that the more parcels they deliver, the more financial losses they incur.
Market Disconnect: The Reality of Artificial Targets
A significant source of friction in the modern courier landscape is the profound disconnect between the growth targets set by corporate headquarters and the actual capacity of regional markets. In many provinces, the combined volume targets established by the five major courier brands far exceed the total available daily outgoing parcel stock. For example, in Wang Bing’s specific region, the total daily outgoing parcel volume is approximately 80,000 units. However, the headquarters of the various delivery companies have set collective targets for their local outlets that total 120,000 units. This creates an impossible scenario where franchisees are forced to compete for a limited pool of business using aggressive pricing strategies that undermine the stability of the entire regional market. The pressure to meet these artificial quotas is enforced through heavy financial penalties, leaving operators with no viable path to sustainable growth.
Faced with these unreachable targets, many franchise operators find themselves trapped in a “lose-lose” scenario regarding their task baselines. If an outlet fails to meet eighty percent of its volume task, it is often fined 1 yuan for every parcel it falls short of the goal. Consequently, operators often engage in a desperate “cost game,” intentionally losing money on parcel collection by offering prices that are below their actual operational costs. It is frequently cheaper for an owner to lose 50 or 80 cents per parcel to secure a shipment than to pay the 1 yuan fine for a volume shortfall. This creates a vicious cycle where local outlets underbid each other to minimize corporate fines, effectively destroying price stability and ensuring that no one in the local network can turn a profit. This environment has transformed the industry from a collaborative logistics network into a cannibalistic struggle for survival.
Profit Divergence: Corporate Gains vs. Outlet Losses
There is a striking and increasingly visible divergence between the financial health of major courier corporate headquarters and the economic stability of their frontline franchise outlets. While the grassroots partners are struggling to remain solvent, the leading enterprises at the top of the pyramid have reported remarkable profit growth. In the first half of 2024, STO Express reported a net profit increase of over 128 percent, while Yunda and YTO Express both saw growth exceeding 70 percent. These gains at the corporate level are largely attributed to “anti-involution” policies that have stabilized high-level pricing and corporate-level cost controls. However, these policies often achieve success by shifting financial and operational burdens downward onto franchisees, who are expected to maintain high service levels while receiving smaller shares of the total revenue.
This structural adjustment has left frontline outlets bearing the brunt of the industry’s growing pains. While headquarters thrive and report record earnings to shareholders, the actual delivery hubs face stricter service assessments and the loss of traditional peak-season protections. Mandatory requirements for door-to-door delivery and phone notifications for every parcel have been implemented without a corresponding increase in delivery fees. This creates an environment where headquarters can market premium service quality to consumers and investors while individual franchise owners must absorb the increased labor costs and complexity required to provide those services. This growing inequality within the delivery network has led many veteran operators to believe that the traditional franchise model is no longer a partnership, but rather an extractive relationship that favors the center at the expense of the periphery.
Operational Pressures: Labor and Service Delivery Standards
The courier industry is currently navigating a mandatory transition toward higher service quality, which has placed immense pressure on the delivery workforce and the owners who manage them. Modern consumers increasingly expect the same level of premium service from affordable franchise couriers that they receive from direct-sale giants like SF Express or JD Logistics. This expectation includes guaranteed door-to-door delivery and precise timing, regardless of the volume of parcels being handled. However, a significant pay gap persists between these different business models; while a direct-sale courier might earn 1.7 yuan per parcel, a franchise courier often earns only 0.9 yuan. This disparity makes it difficult for franchise outlets to retain high-quality staff, leading to higher turnover rates and more frequent customer complaints, which in turn trigger more fines from headquarters.
Operational pressure reaches its peak during major shopping festivals, where recent policy changes have eliminated the historical “buffers” that allowed outlets to manage volume spikes. During the 2024 Double 11 period, many headquarters removed “extension protection,” a policy that previously allowed for slightly longer delivery times during extreme surges in parcel volume. The new mandate requires all parcels to be delivered on the day they arrive at the outlet, regardless of whether the volume has doubled or tripled overnight. This policy forces franchise owners to hire expensive temporary labor and work their existing staff to the point of exhaustion to avoid massive fines for delays. By removing these operational safety nets, the industry has made labor compliance and service standard maintenance nearly impossible for the average franchise owner, further incentivizing experienced operators to exit the market.
Strategic Consolidation: Reconstructing the National Network
The departure of long-term franchisees like Wang Bing is not an isolated event but rather a symptom of a broader trend of network reconstruction and consolidation across the Chinese logistics sector. Data from major courier companies indicates a significant net decrease in the total number of outlets and franchisees over the past year. STO Express recorded a net decrease of 38 outlets, while YTO Express saw a reduction of 83 locations. Even more dramatic shifts occurred at Yunda, which saw a net decrease of 477 first-level franchisees, and J&T Express, which reduced its network partners and outlets by several hundred. This consolidation is often framed by industry leaders as a strategic effort to build an “olive-shaped” service network, where weaker or less efficient outlets are integrated into larger, more stable hubs to create a more competitive and balanced structure.
This period of consolidation signals the definitive end of the “expansion at all costs” era that characterized the previous decade. The market has moved into a “survival of the fittest” phase, where only those with significant capital reserves and high operational efficiency can hope to remain viable. Industry experts suggest that the network is being optimized to remove redundancies and improve the overall quality of service, but this process involves a painful culling of the entrepreneurial class that originally built the system. For many “second-generation” operators who have seen their margins evaporate, selling their business is viewed as a pragmatic move to liquidate a depreciating asset. By exiting when they did, owners like Wang Bing were able to secure several million yuan in capital, successfully preserving their family’s wealth before the cumulative losses of the 2024-2025 cycle could further erode their financial standing.
The Price Mechanism: Why Delivery Fees Continue Falling
Understanding why delivery fees continue to decrease despite rising operational costs is essential to grasping the current courier crisis. The primary driver of this trend is the intense and unrelenting competition among major logistics brands to maintain and expand their market share in a saturated environment. As the “cargo volume dividend” of the early e-commerce boom has largely been exhausted, companies are using aggressive pricing as their primary tool to capture what remains of the market. This results in corporate headquarters lowering the fees they pay to franchise partners to remain competitive on the consumer-facing side of the business. Franchisees, who have little leverage in these negotiations, are forced to accept these lower fees or risk losing their franchise agreement entirely, leading to the razor-thin margins that now define the sector.
Furthermore, the shift toward an automated and data-driven industry has allowed headquarters to squeeze efficiencies out of the network in ways that often disadvantage individual outlet owners. By using sophisticated algorithms to track every movement and every second of a courier’s day, corporate entities have identified ways to lower costs that do not always account for the physical and financial limits of human labor and local management. The relentless pursuit of lower prices for the end consumer has essentially been subsidized by the franchisees and the delivery workers themselves. This price mechanism has created a race to the bottom where quality and sustainability are sacrificed for the sake of volume. Until a more balanced pricing model is established that recognizes the true cost of local delivery and service compliance, the pressure on franchise owners is unlikely to subside.
Future Perspectives: Transitioning Toward Sustainable Service Models
The period leading into 2026 was defined by a fundamental realization that the high-volume franchise model required a complete structural overhaul to survive. Successful operators discovered that moving away from a simple delivery-only business was the only viable path to maintaining profitability. They integrated local industrial resources and transformed their outlets into comprehensive service providers that managed both upstream and downstream logistics for local businesses. This shift allowed them to diversify their revenue streams and reduced their total reliance on shrinking per-parcel fees provided by headquarters. These forward-thinking franchisees also invested heavily in their own local technological infrastructure, using data to optimize routes and labor distribution independently of corporate systems, which ultimately provided a more stable financial foundation during periods of extreme market volatility.
The industry also moved toward a more balanced approach to performance management, as leaders recognized that an over-reliance on punitive fines was threatening the long-term health of the delivery network. New models were introduced that rewarded service quality with financial incentives rather than just penalizing failures, creating a more collaborative relationship between headquarters and the frontline. For those who chose to exit, like the second-generation owners who liquidated their assets, the decision was seen as a strategic pivot into more stable sectors of the digital economy. They redirected their capital into specialized logistics services or e-commerce ventures that offered higher margins and less operational risk. Ultimately, the lessons learned during this crisis period served as the blueprint for a more resilient and standardized logistics industry that prioritized operational efficiency and labor sustainability over the reckless pursuit of sheer volume.