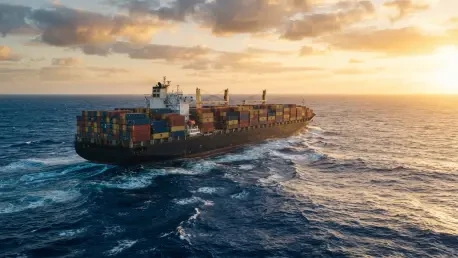
The Bill of Lading serves as a vital transport document in a CIF transaction, acting as the key that allows the buyer to claim their goods once they reach the destination port. In the maritime trade landscape of 2026, this rule provides a structured framework for managing the movement of bulk commodities and non-containerized goods across global waterways. The defining characteristic of CIF is its unique two-point nature, which often creates a point of confusion for those new to international logistics. While the seller is responsible for arranging and paying for the freight to transport the goods to the named port of destination, the risk of loss or damage actually transfers to the buyer much earlier in the journey. Specifically, once the goods are safely loaded on board the vessel at the port of shipment, the buyer becomes financially liable for any incidents that occur during transit. This separation of cost and risk requires a high level of coordination and a clear understanding of the specific obligations established by the International Chamber of Commerce.
Operational Roles and Insurance Requirements
Seller Responsibilities: The Logistics Framework
Under a CIF agreement, the seller assumes the role of the primary logistics coordinator, bearing the responsibility for contracting maritime carriage to the agreed-upon destination port. This duty involves not only paying the freight costs but also managing all necessary export formalities, such as obtaining licenses and clearing the goods for departure. The seller ensures that the cargo is properly delivered on board the vessel, which serves as the fulfillment of their delivery obligation under the 2020 rules.
A standout feature of this maritime term is the mandatory insurance requirement, where the seller must purchase “minimum cover” insurance, known as Institute Cargo Clauses (C), at their own expense. This policy is designed to protect the buyer’s interest during the voyage, allowing them to claim directly from the insurer in the event of major maritime disasters like shipwrecks or fires. By providing the buyer with the insurance certificate and the transport documents, the seller completes their administrative tasks, leaving the physical risk of the ocean crossing to the buyer.
Buyer Obligations: Arrival and Final Distribution
The buyer’s role becomes active the moment the goods are secured on the vessel at the origin, as they now carry the financial burden for the cargo’s safety. While the seller handles the initial shipment, the buyer must be prepared to manage the arrival process at the destination port. This includes paying for any unloading costs that are not covered by the freight contract and ensuring that the arrival of the vessel is coordinated with their local logistics partners. The risk transfer at the origin means the buyer must be diligent in verifying the insurance provided by the seller.
Upon arrival, the buyer is solely responsible for navigating the complexities of customs clearance and settling all import duties and local taxes. Beyond the port, the CIF rule does not cover any inland transportation, meaning the buyer must arrange and fund the movement of goods to their final facility or laboratory. This requires a comprehensive understanding of local regulations and the procurement of domestic transport services to complete the supply chain. Successful buyers often use this transition point to conduct a final inspection of the goods before moving them into their inventory.
Industry Comparisons and Sector-Specific Challenges
Comparative Analysis: CIF Versus Alternative Rules
To utilize CIF effectively, it is helpful to compare it to similar rules like CIP and FOB. While CIP (Carriage and Insurance Paid To) mirrors the cost-and-insurance structure of CIF, it is a multimodal term that can be used for any mode of transport and requires a higher level of “all-risks” insurance coverage. In contrast, CIF is strictly reserved for water transport and provides only basic insurance. This distinction is vital for businesses shipping high-value electronics or machinery that require more comprehensive protection than Clause (C) provides.
Compared to FOB (Free On Board), where the buyer handles the freight and insurance themselves, CIF offers a more streamlined pricing model that can be advantageous for buyers without extensive logistics departments. However, many experienced traders prefer FOB because it gives them greater control over the shipping lines and the actual cost of the freight. Choosing between these terms often depends on the buyer’s internal infrastructure and their willingness to manage the administrative tasks associated with global shipping. In the current market of 2026, the preference for CIF remains strong in the bulk commodity sector due to its established history and simplicity.
Specialized Applications: Medical and Scientific Logistics
In specialized fields such as laboratory science and healthcare, the standard CIF rules often require additional contractual safeguards to meet industry needs. Because CIF only mandates “minimum cover” insurance, it may not adequately protect sensitive scientific instruments or expensive reagents against theft or minor damage. Procurement officers in these sectors frequently negotiate for higher levels of insurance, such as Clause (A), to ensure full protection. This is particularly important when shipping specialized diagnostic equipment that is sensitive to the harsh conditions of a long maritime voyage.
Furthermore, the “sea-only” restriction of CIF makes it an incorrect choice for time-sensitive medical supplies that must be shipped via air. If a shipment requires temperature control, such as a cold chain for biological materials, these requirements must be explicitly added to the sales contract. The Incoterms rule itself does not address environmental factors, so the responsibility for maintaining a specific temperature range must be clearly assigned to ensure cargo integrity. This level of detail ensures that critical supplies arrive in a usable condition, preventing costly delays in research or patient care.
Strategic Implementation: Practical Takeaways and Future Steps
The successful management of CIF transactions required a thorough evaluation of the specific risks associated with maritime corridors and the adequacy of the mandated insurance. Stakeholders identified that relying solely on the default Clause (C) coverage often left high-value shipments vulnerable to common transit issues like pilferage or water damage. Consequently, many organizations established protocols to upgrade their insurance requirements in the initial sales agreement. This proactive approach ensured that financial recovery was possible even for minor damages that fell outside the scope of basic maritime disasters.
Moving forward, businesses optimized their logistics by strictly aligning the chosen trade term with the actual mode of transport used for the shipment. They also prioritized the timely exchange of the Bill of Lading and other transport documents to avoid expensive storage fees at the arrival port. By clearly defining the unloading responsibilities and inland transport costs, companies reduced the friction often found at the interface between international and domestic logistics. These strategic adjustments allowed traders to maintain better control over their supply chains and ensured that the delivery process remained both efficient and legally secure.