The shift toward omnichannel fulfillment allows retailers to use their entire physical footprint to compete directly with specialized logistics providers. This structural reconfiguration is not merely a tactical adjustment but a fundamental response to the “Amazon Effect” that has redefined the baseline of consumer expectations in 2026. In the current landscape, the historical trade-off between speed, cost, and accuracy has effectively vanished, replaced by a non-negotiable demand for all three facets of service simultaneously. As a result, the parcel express market, which remained static for decades under a few national players, has fractured into a highly volatile and tech-enabled ecosystem. Shippers are no longer satisfied with rigid, monolithic delivery schedules provided by legacy carriers; instead, they are seeking fragmented, agile solutions that prioritize regionalization and data-driven inventory placement. This evolution is forcing every participant in the supply chain to rethink their infrastructure, moving away from centralized hub-and-spoke models toward micro-fulfillment and localized nodes that can facilitate same-day or next-day delivery without the exorbitant costs traditionally associated with expedited shipping. The stakes are higher than ever, as the inability to adapt to this tech-driven reality often results in immediate loss of customer loyalty and market share to more nimble competitors.
Software Democratization: Breaking the Duopoly Barrier
Historically, the high barriers to entry in the logistics industry were maintained by the massive capital requirements needed for nationwide routing software and physical infrastructure. National giants like UPS and FedEx enjoyed a long-standing dominance because small-to-mid-sized enterprises simply could not afford the technological complexity required to manage a distributed delivery network. However, the rise of the gig economy coupled with the availability of low-cost, high-powered multicarrier management software has fundamentally leveled the playing field. These modern platforms allow shippers to bypass traditional gatekeepers by orchestrating complex logistics workflows from a single dashboard. By integrating with various regional carriers and local couriers through standardized APIs, even smaller retailers can now access shipping rates and delivery speeds that were once the exclusive domain of Fortune 500 companies. This democratization of technology has transformed logistics from a cost-heavy burden into a strategic asset, enabling a new wave of regional players to emerge and challenge the market share of established national carriers who are struggling to maintain their profit margins amidst rising labor costs and operational overhead.
Predictive Logistics: The Power of AI-Enabled Micro-Fulfillment
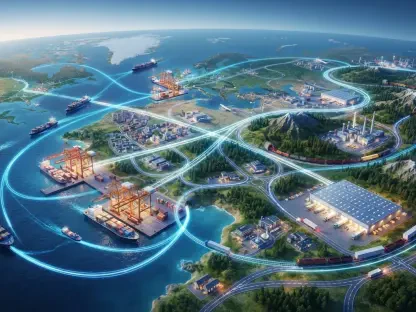
Building on this foundation, AI-enabled optimization tools are now facilitating more sophisticated inventory placement strategies, such as micro-fulfillment. These technologies allow businesses to predict demand patterns with surgical precision, ensuring that the right products are staged in small, localized “micro-sites” or urban warehouses before a customer even places an order. By utilizing artificial intelligence to analyze historical data, seasonal trends, and local purchasing behaviors, retailers can minimize the “last mile” distance—the most expensive and complex part of the shipping process. This move toward localized inventory reduces the miles a package must travel, which is currently the most effective way to combat rising fuel surcharges and carrier rates. Furthermore, asset-light technology platforms enable businesses to manage these distributed supply chains without the need to own their own delivery vans or warehouses. This flexibility allows for a rapid scaling of operations that matches consumer demand in real-time, providing a level of responsiveness that traditional hub-and-spoke models cannot replicate. The result is a more resilient supply chain that prioritizes proximity to the end consumer, effectively turning the entire geography into a vast, interconnected distribution network.
Retailers as Competitors: The Expansion of Private Fleets
The carrier landscape has undergone a radical fragmentation, moving away from a simple choice between two or three national providers toward a diverse array of specialized delivery options. While the national giants still maintain extensive physical assets, their dominance is being eroded by the massive internal delivery networks of companies like Amazon and Walmart. In 2026, Walmart’s store-to-home delivery network now covers approximately 93% of the U.S. population, demonstrating how major retailers are transitioning into formidable logistics competitors. These private fleets are not just serving their own customers; they are increasingly offering third-party logistics services, further tightening the competition for traditional parcel carriers. Alongside these corporate giants, a new breed of regional and local players has emerged, focusing on specific geographic niches or industry-specific requirements like healthcare, perishables, and high-end apparel. These carriers often offer more competitive rates and better service reliability within their target areas because they do not have the overhead costs of maintaining a nationwide network. This diversification allows shippers to build a “carrier quilt,” selecting the most efficient provider for each specific lane and package type rather than relying on a single, expensive national contract.
Global Integration: International Entrants and Parcel Consolidation
In addition to domestic shifts, the North American market is seeing an influx of well-funded international entrants, particularly from Asia. These carriers, often backed by significant Chinese capital, are capitalizing on the surge of cross-border e-commerce, providing streamlined logistics for packages flowing from overseas marketplaces directly to American doorsteps. Their entry has introduced a new level of price competition, especially in the high-volume, low-margin segments of the market. To manage this influx and variety of carriers, consolidators and intermediate players have become essential components of the modern supply chain. These entities pool parcels from multiple small and mid-sized shippers to create the bulk volumes necessary to negotiate better rates. These aggregated parcels are then “injected” into carrier networks at the most efficient entry points, such as local sorting hubs, bypassing unnecessary steps in the traditional national sorting system. This injection model maximizes efficiency for the final-mile carrier and significantly reduces costs for the shipper. As the market continues to fracture, the ability to navigate this complex web of international, national, and regional providers has become a primary differentiator for successful retailers who prioritize shipping speed and cost-effectiveness.
Financial Turbulence: Navigating the Complexity of Surcharges
Pricing has evolved into the most significant challenge for modern shippers, characterized by extreme volatility and an increasing reliance on complex surcharge structures. In an environment where carrier fuel surcharges, peak delivery fees, and residential surcharges are adjusted with high frequency, the “sticker price” of shipping is rarely the final cost. Major national carriers have adjusted their rates or added new fees dozens of times over the last few years, creating a climate of uncertainty that makes long-term budgeting nearly impossible for many businesses. This volatility is compounded by the fact that overall parcel volumes have leveled off, forcing carriers to implement more aggressive pricing strategies to defend their profit margins. Consequently, the traditional model of securing deep discounts through high-volume commitments is losing its effectiveness. Shippers are finding that the “all-in” cost of shipping is often higher than expected once all surcharges are applied, leading many to realize that putting all their logistics needs into a single basket is a risky and expensive strategy. The focus has shifted from simple rate negotiation to a more granular analysis of every line item on the shipping invoice, requiring sophisticated auditing tools to ensure that carriers are adhering to their contract terms.
Dynamic Pricing: Leveraging APIs for Real-Time Savings
To combat these rising costs, the industry is seeing the emergence of innovative pricing models driven by real-time data and API connectivity. One of the most promising developments is the rise of dynamic savings programs, which allow carriers to offer lower rates when they have excess capacity in specific geographic lanes. Instead of fixed contract rates, these programs use real-time market data to offer discounts that can reach up to 15% below standard contract ceilings. This creates a mutually beneficial scenario: carriers can increase their network density and fill their vehicles more efficiently, while shippers can significantly reduce their overhead by moving packages during periods of lower demand or higher carrier availability. These technology-driven pricing strategies allow for a level of financial agility that was previously impossible in the logistics world. Shippers can now use multicarrier management software to compare the total landed cost of a delivery—including all surcharges—in real-time across multiple providers. This data-driven approach allows businesses to make the most cost-effective choice for every individual shipment, effectively neutralizing the impact of rising general rate increases. By leveraging these digital tools, savvy shippers are transforming their logistics departments from cost centers into drivers of operational efficiency.
Future Projections: Preparing for the 2028 Parcel Tsunami
Looking toward the horizon, the parcel industry faces a looming disruption often described as a “parcel tsunami,” which is set to fundamentally reshape the hierarchy of market power by 2028. This potential upheaval is largely centered on the intensifying labor negotiations within national carrier networks and the rapid expansion of private logistics infrastructure. As labor costs for traditional carriers continue to rise, they risk losing their competitive edge to more automated, lower-cost competitors. If the legacy giants cannot align their operational costs with the leaner, tech-first models utilized by firms like Amazon, they may face a rapid erosion of their core business segments. By the end of the decade, it is projected that Amazon’s parcel volume could exceed the combined output of the current top national carriers, representing a total reversal of the traditional industry structure where a single customer becomes the dominant force. This shift will likely force a consolidation among smaller regional players and a renewed focus on specialized service niches. For shippers, this means the competitive landscape will only become more complex, requiring a proactive approach to carrier diversification and a deep commitment to integrating emerging logistics technologies into their core business operations.
Network Density: The Key to Operational Excellence
The transition toward a more fragmented and technologically advanced parcel market demanded a fundamental shift in how businesses approached their logistics strategies. Historically, the reliance on a single national carrier was sufficient, but the volatility of the recent years proved that agility and data-driven decision-making were the only sustainable paths forward. Successful organizations abandoned rigid shipping models and instead embraced a “carrier quilt” strategy that utilized a mix of national, regional, and private networks. They implemented sophisticated multicarrier management software to navigate the complexity of rising surcharges and exploited dynamic pricing to protect their profit margins. Moving forward, businesses should prioritize the localization of their inventory through micro-fulfillment nodes to further reduce last-mile distances and costs. It is essential to continuously audit carrier performance and pricing data to ensure that logistics expenditures remain optimized against shifting market conditions. By leveraging AI-driven predictive analytics, shippers can stay ahead of demand surges and labor disruptions, ensuring that delivery promises are kept even in a volatile environment. The path to long-term success involves not just adopting new tools, but fostering a culture of operational flexibility that views logistics as a dynamic, tech-powered competitive advantage rather than a static operational expense.