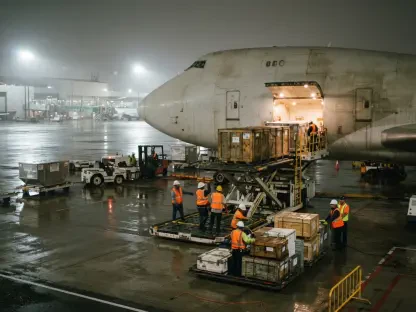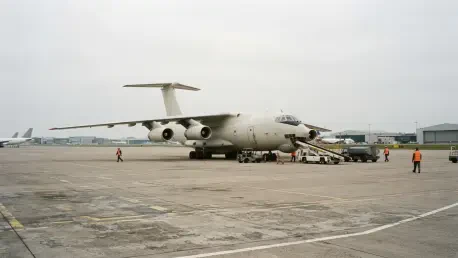
Carrier pricing power has strengthened significantly as global cargo load factors climbed to 47.9% amid a persistent lack of system-wide capacity, while the air cargo sector between Asia and North America has emerged as the primary engine of global trade growth. This transpacific lane outperformed the broader international market during the third quarter of 2026, recording a 17% year-on-year increase in freight volume and marking an impressive eighth consecutive month of expansion. This growth rate remains particularly striking when compared to the global average of 7.7%, signaling a concentrated shift in trade dynamics toward direct transpacific routes that prioritize speed and reliability. As shipping lanes elsewhere experience varied levels of volatility, the corridor connecting Asian manufacturing hubs to North American consumers has maintained unprecedented momentum, forcing logistics providers to rethink their traditional hub-and-spoke models in favor of more robust direct service offerings across the ocean.
Market Dynamics and Imbalances
Supply and Demand Trends
A central theme in the current market remains the widening gap between the massive appetite for air freight and the limited available space on wide-body aircraft. While global demand rose steadily throughout the year, total capacity expanded at a much slower rate of only 2.7%, creating a severe mismatch that fundamentally altered negotiation dynamics between shippers and carriers. This imbalance has directly resulted in tightening load factors, granting airlines significant leverage during contract renewals and spot market pricing. In a network operating at near-total capacity, any additional surge in volume—whether driven by organic growth or temporary market shifts—immediately translates into higher yields rather than an increase in total tonnage moved. Shippers have found themselves competing for scarce space, often being forced to pay premium rates to ensure their cargo makes it onto scheduled flights without being bumped for higher-yielding shipments from competitors.
Regional Performance Shifts
The dominance of the transpacific corridor is causing a notable realignment in global shipping patterns, particularly at the expense of traditional transit hubs that once thrived on intercontinental stopovers. Cargo is increasingly bypassing Middle Eastern and European transit points in favor of direct flights to North American gateways to save time on high-value, time-sensitive shipments. While other regions like Latin America and Africa show varied performance with modest growth, the current boom remains a concentrated phenomenon centered on the Pacific. This shift is likely driven by the need to minimize handling and transit times for electronics and high-tech components produced in East Asia. As direct routes become the preferred choice for major exporters, traditional “middle-ground” hubs must adapt to a landscape where speed is prioritized over the cost savings of consolidated routing, leading to a significant redistribution of aircraft assets and flight frequencies across major global air carriers.
Primary Growth Drivers
Technological Infrastructure Needs
The most stable driver of this growth is the massive surge in semiconductor and artificial intelligence hardware production, which reached new heights in late 2026. These components are high-value, time-sensitive, and compact, making them ideal for air transport rather than slower and more vulnerable ocean freight options. Because this demand is tied to long-term technological investment cycles and the global race for AI supremacy, it provides a structural foundation for the air cargo market that is less prone to sudden consumer fluctuations. As manufacturing facilities in Taiwan, South Korea, and Japan ramp up production to meet the global demand for next-generation chips, the air cargo bridge to North America remains the essential link in the supply chain. This technological demand acts as a persistent floor for volumes, ensuring that even during seasonal lulls, the transpacific lane remains occupied by high-density, high-margin freight that requires climate-controlled and secure air transport solutions.
E-commerce and Tariff Strategy
A significant portion of the recent volume spike is attributed to “frontloading,” where importers accelerate their shipping schedules to move goods before new trade duties or regulatory changes take effect. This behavior creates an artificial surge in monthly figures that reflects defensive maneuvering rather than just organic consumer growth. While e-commerce remains a massive volume driver, it is highly reactive to regulatory signals and trade policy shifts, often leading to volatile month-to-month performance that complicates long-term planning for carriers. Shippers are currently prioritizing the immediate arrival of goods to insulate themselves against potential cost increases, leading to a crowded market where “speed to border” is the primary objective. This rush to secure inventory before policy deadlines has tightened the market even further, leaving little room for smaller players to find affordable capacity as large e-commerce platforms monopolize available belly space and freighter slots for their urgent cross-border deliveries.
Operational Hurdles
Escalating Operating Costs
Despite high demand and strong pricing power, airlines face significant headwinds regarding their core operating expenses, which have reached challenging levels. Jet fuel prices have seen a massive year-on-year spike, creating a paradoxical situation where carriers move record volumes but struggle to maintain healthy operating margins. These rising input costs influence critical network decisions, often forcing airlines to prioritize cargo-heavy routes over traditional passenger services to maximize revenue per flight hour. The increased cost of labor and ground handling services has further squeezed the bottom line, requiring carriers to implement sophisticated fuel surcharges and dynamic pricing models to remain profitable. For many operators, the high revenue generated by the Asia–North America lane is the only factor keeping their overall cargo divisions in the green, as the expenses associated with maintaining a modern freighter fleet continue to climb alongside the global inflationary pressures affecting the entire aviation industry.
Capacity Constraints and Yields
The persistent lack of “slack” in the system means that any additional surge in volume immediately results in higher yields and increased costs for shippers who are already stretched thin. On transpacific routes, dynamic load factors have reached near-total capacity, leaving little room for error or sudden market shifts that would typically be absorbed by a more flexible network. This environment requires shippers to navigate a market characterized by high prices and zero flexibility in logistics planning, where missing a single booking window can lead to weeks of delays. Yield management has become the primary focus for airline executives, who are utilizing advanced data analytics to squeeze every possible dollar from their available pallet positions. This focus on yield optimization has marginalized lower-value commodities, which are increasingly being pushed toward ocean freight as air transport becomes a luxury reserved for the most urgent or expensive goods that can justify current market rates.
Future Market Outlook
Long-Term Sustainability
The critical test for the air cargo industry centered on whether volumes remained high after the initial rush to beat tariff deadlines passed. If the market stayed robust, it confirmed that the structural demand for artificial intelligence and high-tech hardware was strong enough to support the industry independently of political shifts. Analysts looked for signs of stabilization in order volumes to determine if the 17% growth rate was a sustainable trend or a temporary bubble caused by defensive inventory positioning. Shippers who transitioned to long-term block space agreements fared better than those relying on the volatile spot market, which experienced dramatic swings throughout the year. The ability of carriers to maintain these high load factors depended heavily on the continued rollout of new technology products and the steady consumption of electronics in the North American market. Observers noted that the industry’s resilience was tested by fluctuating consumer confidence levels and the evolving global trade landscape.
Strategic Industry Implications
The industry recognized that the perfect storm of industrial demand and inventory positioning required a permanent change in how high-value goods moved across the globe. Logistics managers were encouraged to diversify their transit routes and invest in predictive analytics to better anticipate capacity crunches before they occurred. The long-term health of the Asia–North America trade lane depended on the stabilization of trade policies and the continued expansion of the semiconductor lifecycle. Moving forward, the industry balanced record-breaking demand against the realities of extreme capacity tension and doubling fuel costs. Companies that successfully integrated multimodal solutions, combining air and sea transport, managed to mitigate some of the extreme costs associated with the peak season. Stakeholders prioritized the development of more fuel-efficient freighter fleets to protect margins against future energy price spikes. These strategic shifts ensured that the transpacific corridor remained the backbone of global commerce for the foreseeable future.