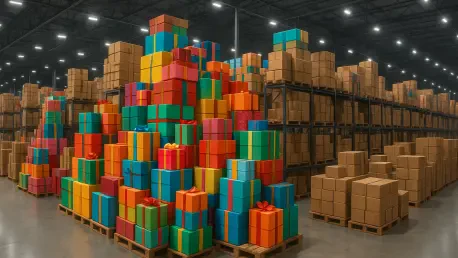
The rhythmic hum of automated warehouses currently conceals a mounting financial tension as retailers gamble billions on holiday inventory that arrived months before the first snowflake fell. This strategic maneuver, known as frontloading, represents a significant departure from lean logistics, as companies prioritize stock availability over liquidity to buffer against geopolitical trade shifts and potential tariff hikes. By securing merchandise well in advance of traditional peak windows, businesses are effectively betting on a consumer demand curve that has yet to be fully defined. This analysis explores the profound financial and operational consequences of this trend, particularly the hidden costs of warehouse stagnation and the risk of a mismatch between supply and actual spending. By examining the lifecycle of excess inventory and the shift toward sophisticated secondary-market strategies, stakeholders can uncover how brands must adapt to maintain liquidity in a market defined by unpredictable discretionary spending and a narrowing window for profitability.
Supply Chain Precaution: The Motives Behind Early Stocking
To understand the current inventory landscape, one must look at the recent disruptions that have reshaped global logistics. For years, the “just-in-time” model was the gold standard, minimizing carrying costs by timing deliveries closely with demand. However, the post-pandemic era, marked by port congestion and geopolitical instability, forced a pivot toward “just-in-case” strategies. These historical shifts have set the stage for the current frontloading phenomenon, where the fear of empty shelves outweighs the fear of overstock. Retailers are no longer just fighting for market share; they are fighting for certainty in an era where trade routes can be disrupted overnight. These background factors matter because they have fundamentally altered the “cost of being wrong.” When inventory arrives early, the financial stakes are magnified, as the time between capital expenditure and revenue realization stretches, creating a vulnerability that did not exist in the leaner retail environments of the past.
The Financial Weight: Carrying Costs and Capital Stagnation
The primary challenge facing modern retailers is not merely the volume of goods, but the timing of their arrival. By bringing in holiday merchandise early, businesses have significantly increased their financial exposure before the shopping season even begins. Every week an item sits in a warehouse, it consumes valuable storage capacity and ties up essential working capital that could be used for other operational needs. This creates a compounding financial burden where carrying costs—including insurance, labor, and facility overhead—slowly erode the profit margins of the products. If the inventory does not move at the expected velocity, the risk of obsolescence grows, particularly in fast-moving sectors like fashion and consumer electronics. The strategic priority must therefore shift from simple procurement to ensuring that stagnant goods are transformed back into cash as quickly as possible to preserve a healthy balance sheet.
The Compounding Burden: How Storage Expenses Erode Profit Margins
The accumulation of goods in warehouses leads to more than just a lack of floor space; it triggers a cascade of secondary costs that are often overlooked during the initial procurement phase. As facilities reach capacity, retailers are forced to seek overflow storage, often at premium spot rates, which further increases the per-unit cost of inventory. Moreover, the labor required to manage and move stagnant stock adds a layer of operational friction that slows down the entire supply chain. This stagnation is particularly dangerous because it prevents the reinvestment of capital into fresh, trend-aligned products. When capital is locked in a warehouse for six months instead of two, the opportunity cost becomes a tangible drag on the overall financial health of the organization, making the recovery of value a race against the calendar.
Market Vulnerabilities: Demand Fluctuations in Discretionary Categories
Certain segments of the retail market are more susceptible to the risks of overstocking than others. Apparel, home goods, and electronics are particularly vulnerable because they rely heavily on discretionary spending. Unlike essential goods, consumers can easily delay these purchases or seek lower-priced alternatives if economic conditions tighten or if their preferences shift unexpectedly. This behavioral flexibility makes demand forecasting notoriously difficult, especially when goods are ordered half a year in advance. A significant risk identified in this environment is the “promotional trap,” where retailers rely on aggressive in-store discounting to move early stock. This strategy often backfires by training consumers to wait for markdowns, which erodes brand equity and creates a cycle where full-price sales become a rarity. To mitigate this, retailers are increasingly segmenting their inventory early to identify which items should be moved to secondary channels rather than devaluing the primary brand through endless sales.
Secondary Market Evolution: Strategic Disposition in the Digital Era
The traditional approach to excess inventory—waiting until after the holiday season to liquidate—is becoming obsolete as the industry recognizes the value of early intervention. Experts suggest that the time to plan for secondary-market disposition is well before the peak shopping season begins, allowing for a more controlled and profitable exit. Modern secondary markets have evolved into sophisticated digital platforms that facilitate competitive bidding among a vast network of vetted buyers. This shift allows the market to determine the fair value of excess goods, often resulting in higher recovery rates than a single-liquidator deal. Furthermore, these platforms provide retailers with the control and transparency needed to protect their brand. By stipulating where and to whom goods are sold, companies can prevent secondary market sales from cannibalizing their primary retail channels, turning a potential liability into a strategic asset that supports long-term liquidity.
Future Projections: Predictive Logistics and Regulatory Shifts from 2026 to 2028
Looking ahead, the retail industry is likely to see an increased reliance on predictive analytics and artificial intelligence to better align frontloaded inventory with hyper-local demand. From 2026 to 2028, we can expect innovations in “inventory velocity” tracking, where automated systems trigger secondary-market sales the moment an item falls behind its expected sales curve. Additionally, regulatory changes regarding trade and tariffs will continue to dictate how aggressively retailers frontload their stock. Experts predict that the secondary market will no longer be viewed as a “last resort” for failed products but will become a permanent, integrated component of a circular retail economy. As warehouse space remains at a premium, the ability to rapidly offload returned or excess goods will become a core competitive advantage for major brands seeking to stay agile in a volatile global market.
Strategic Recommendations: Navigating Risks Through Precision and Speed
To successfully manage the risks of early inventory, retailers should focus on several key takeaways and best practices. First, prioritize velocity over volume; success is defined by how quickly capital can be recycled back into the business. Second, implement proactive segmentation by establishing “triggers” that move slow-moving stock to secondary channels before its value bottoms out. Third, diversify disposition channels to avoid the “pileup” that occurs when traditional liquidators reach their capacity during the post-holiday return surge. Businesses should also invest in transparent secondary-market platforms to maintain brand integrity while recovering value. By applying these strategies, professionals can navigate the “cost of being wrong” with greater agility and financial resilience, ensuring that early preparation does not lead to long-term stagnation.
Long-Term Outlook: Ensuring Resilience Through Proactive Management
The decision to frontload holiday inventory was a double-edged sword that offered protection against supply chain shocks while introducing significant financial strain. The analysis showed that the winners of this retail cycle were those who managed their excess stock with the most precision and speed. The significance of this topic remained high because the global trade environment continued to be unpredictable, making sophisticated inventory management a permanent necessity rather than a seasonal fix. Retailers that moved beyond reactive discounting and embraced a proactive, multi-channel approach to inventory disposition found themselves in a much stronger position. In the modern retail landscape, agility was the ultimate currency, and the ability to turn a potential overstock crisis into a streamlined recovery process separated the market leaders from those left behind. Moving forward, the integration of secondary markets into primary planning became the standard for maintaining long-term financial stability.