The modern electronics landscape has reached a critical juncture where the ability to source a single high-performance memory chip often dictates the quarterly success of a multi-billion-dollar enterprise. This shift is not merely a temporary reaction to market fluctuations but represents a fundamental rewiring of global manufacturing logic. In 2026, the sector continues to navigate a transformation characterized by extreme price volatility and a radical departure from the lean models of the previous decade. For years, the industry relied on the absolute predictability of the global supply chain, but the recent memory supply crisis, which saw costs skyrocket by 400%, changed the calculus for every major player. Manufacturers are now forced to choose between absorbing massive losses or reinventing their operational DNA to accommodate a more fragmented reality. This analysis explores how firms are abandoning reactive tactics in favor of sophisticated, long-term operational resilience. By examining the shift toward premiumization, strategic alliances, and regionalization, we can understand the new blueprint for an industry that must now prioritize stability over mere affordability.
Navigating the New Normal: Global Electronics Manufacturing
The global electronics industry is currently navigating a period of profound transformation characterized by volatility, scarcity, and strategic reorganization. For decades, the sector thrived on a “just-in-time” model that prioritized low costs and lean inventories above all other metrics. However, a series of global shocks—from the unprecedented memory supply crisis to the explosive demand for Artificial Intelligence (AI) infrastructure—has rendered these old strategies obsolete. This period of instability has exposed the hidden costs of efficiency-first models, forcing a realignment of corporate priorities toward risk mitigation.
Major manufacturers are no longer looking for the cheapest possible component; instead, they are seeking the most reliable path to procurement. This involves a total overhaul of how demand is forecasted and how goods are moved across borders. The industry is witnessing a shift where operational resilience is the new competitive advantage. As companies reorganize their production lines and logistics networks, they are creating a more robust framework that can withstand the demand spikes associated with the rapid expansion of high-capacity data centers and next-generation consumer devices.
Efficiency versus Resilience: The Historical Shift in Supply Management
To understand the current state of the electronics supply chain, one must look back at the historical emphasis on cost-optimization that defined the last twenty years. Historically, the industry was built on highly centralized manufacturing hubs and a reliance on single-source suppliers to maximize economies of scale and drive down unit costs. These foundational concepts worked well in a stable geopolitical and economic environment, but they created significant vulnerabilities that remained hidden until the system was pushed to its breaking point. The reliance on thin margins and zero-stock policies left no room for error when global shipping lanes faced disruption or when demand for specific silicon components suddenly doubled.
The background of the current “memory crunch” and the rapid expansion of modern computing have highlighted how these legacy systems fail when faced with simultaneous demand spikes and supply bottlenecks. Recognizing these background factors is essential because it explains why the industry is now undergoing a “renaissance in planning.” Leaders are moving away from day-to-day scrambling toward multi-year strategic roadmaps that treat supply chain health as a core financial asset. This shift marks the end of the era where the supply chain was viewed as a cost center to be minimized, transforming it instead into a strategic pillar of corporate longevity.
Strategic Responses: Persistent Market Volatility
Advanced Planning Systems: The Integration of AI
A critical aspect of the modern electronics supply chain is the move toward a “renaissance in planning discipline” that utilizes cutting-edge technology to predict market movements. During the early post-pandemic period, many firms regressed into tactical, short-term decision-making to survive immediate shortages. However, current market pressures have necessitated a return to multi-year strategic roadmaps that integrate inventory management with long-term investment cycles for the period from 2026 to 2029. To achieve this, major electronics firms are reinvesting in advanced planning software from established vendors like SAP, Blue Yonder, and Kinaxis.
The integration of AI into these systems is no longer a luxury; it is a requirement for “demand sensing.” This technology allows manufacturers to analyze vast datasets, from social media trends to geopolitical developments, to predict shifts in consumer interest and fulfillment needs with greater precision. This creates an “always-on” responsiveness that helps the industry withstand external shocks. By using AI to create digital twins of their supply networks, companies can run thousands of simulations to identify potential points of failure before they occur, allowing for a proactive approach to inventory building.
Evolution of Product Design: Premium Market Mixes
As the cost of raw materials and specialized components continues to climb, electronics brands are finding that traditional cost-cutting is no longer sufficient to maintain profitability. Consequently, the industry is witnessing a fundamental change in product design and market positioning. High-profile companies are retreating from low-margin, budget-friendly devices, focusing instead on high-end, premium products that offer higher profit margins. This shift toward “premiumization” allows manufacturers to absorb the high costs of constrained components while still delivering value to a less price-sensitive consumer segment.
This trend often involves material innovation to navigate the complex web of international trade laws and tariffs. For example, some manufacturers are switching from expensive aluminum casings to specialized high-grade plastics or composite materials to manage costs and avoid supply bottlenecks associated with metal trade restrictions. By focusing resources on the luxury segment, companies are effectively passing the burden of component scarcity onto the high-end market while maintaining their bottom lines. This strategy ensures that limited component allocations are used for the most profitable products, maximizing the return on every microchip secured.
Deep Integration: Strategic Supplier Alliances
The power dynamics between manufacturers and suppliers have fundamentally altered, leading to highly integrated, long-term partnerships that look very different from the transactional relationships of the past. The standard one-year contract is becoming a relic, replaced by agreements spanning three to five years. These new arrangements often involve significant financial commitments, such as advance payments of up to 30% of the total contract value to secure priority status during times of peak demand. This trend favors massive industry players with the balance sheet capacity to lock in supply years in advance, creating a stratified market where the largest firms have the most secure futures.
These partnerships are not merely transactional; they often involve “take-or-pay” agreements and joint ventures that ensure both parties are deeply invested in the long-term provenance and resilience of the supply chain. In some cases, electronics manufacturers are even investing directly in the construction of new fabrication facilities for their suppliers. This deep integration provides a level of transparency that allows both sides to share risks and rewards, ensuring that the supplier has a guaranteed buyer and the manufacturer has a guaranteed source of critical components like custom silicon and advanced memory modules.
Future Trends: Regionalization and the New Logistics Paradigm
Emerging trends suggest that the electronics supply chain will continue to move toward a more fragmented but robust global infrastructure. One of the most significant shifts is “regionalization”—the practice of producing goods closer to their end markets to mitigate geopolitical risks and reduce overexposure to any single country. By establishing manufacturing clusters in North America, Europe, and Southeast Asia simultaneously, firms can bypass regional disruptions and reduce the carbon footprint of their logistics. This diversification is a direct response to the realization that a globalized, single-source model is too fragile for the current geopolitical climate.
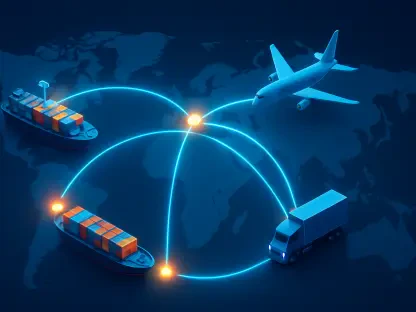
Furthermore, a paradigm shift is occurring in logistics where availability is now prioritized over cost. While ocean freight remains the base flow for stable, high-volume orders, firms are increasingly maintaining “expedite lanes” via air freight for critical, constrained components. Expert predictions suggest that the successful electronics company of the future will not be the one with the cheapest supply chain, but the one with the most transparent and geographically diverse network. This “hybrid” logistics model ensures that even if one major shipping lane is blocked, the most vital parts can still reach the assembly line to prevent a total production halt.
Strategic Takeaways: A Volatile Industry
The analysis of the current electronics landscape provides several actionable strategies for businesses and professionals navigating this complexity. First, the transition from “just-in-time” to “just-in-case” resilience is mandatory for survival; companies must be willing to pay a premium for supply security and carry larger buffer stocks of critical components. Second, diversifying the supplier base and moving away from single-sourcing models is essential to prevent production halts during regional disruptions. Relying on a single vendor, regardless of how efficient they are, is now recognized as a major operational risk.
Finally, leveraging AI for demand sensing and maintaining deep, multi-year relationships with vendors are the best practices for managing modern scarcity. For consumers, these shifts mean that while product availability may stabilize, the era of “premiumization” will likely result in higher costs for cutting-edge technology. Professionals should focus on building supply chains that are not just lean, but “intelligent,” using data to bridge the gap between procurement and end-user demand. Investing in regional manufacturing capacity will also be a key differentiator for companies looking to maintain a stable market presence from 2026 to 2030 and beyond.
Building a Robust Future: Global Electronics
The electronics industry successfully navigated a period of extreme turbulence by fundamentally altering its approach to global operations. The shift toward premiumization and long-term supplier alliances proved to be the most effective way to manage the skyrocketing costs of essential components. Managers realized that the old models of cost-optimization were insufficient when faced with the dual pressures of AI-driven demand and geopolitical instability. They implemented regionalized manufacturing hubs and integrated advanced planning software to ensure that the supply chain remained resilient even under pressure.
These strategic actions provided the stability necessary to continue technological innovation despite the memory supply crisis. Moving forward, the focus remained on transparency and geographic diversity, ensuring that the industry could withstand future shocks while supporting the next generation of data-driven growth. The adoption of these strategies ensured that manufacturers stayed competitive in a market that no longer tolerated fragility. Ultimately, the ability to adapt to crisis ceased to be a defensive maneuver and became the ultimate competitive advantage, ensuring that the technology of tomorrow was built on a foundation of reliability and strategic foresight.